


TOKYO –
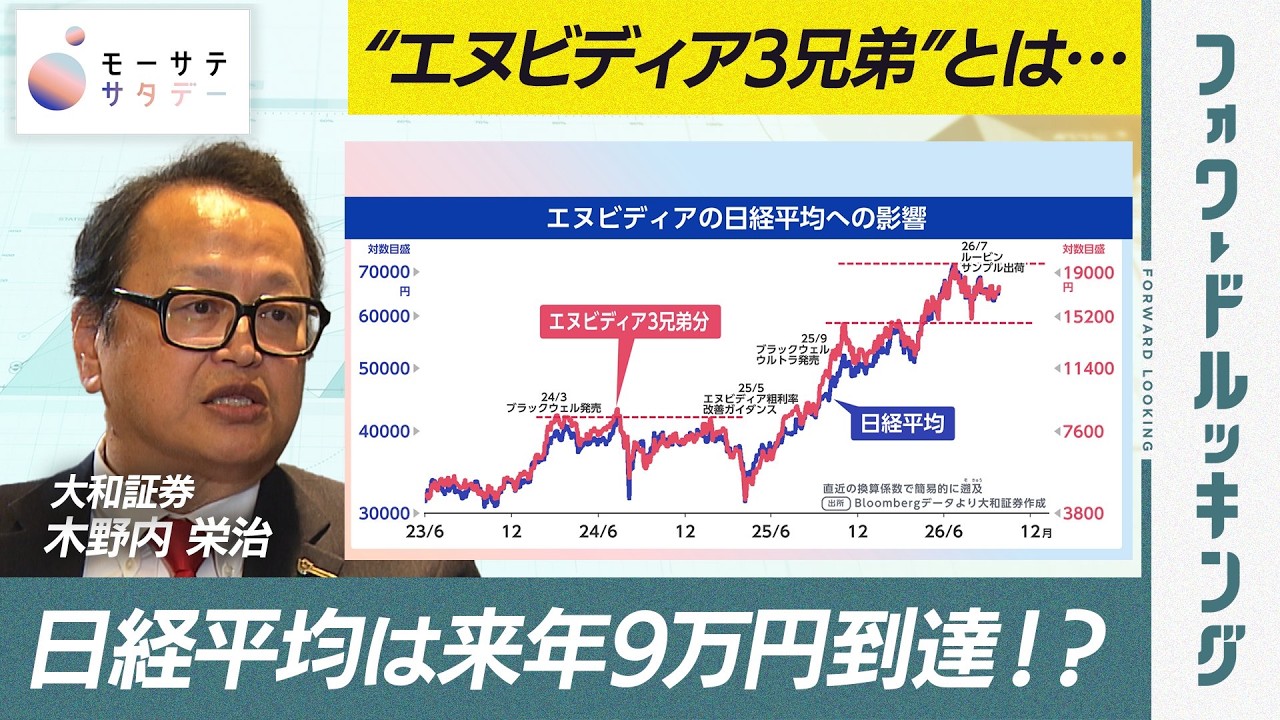
Tokyo shares head into September 28 with the Nikkei 225 sitting at 66,364 after a five-session successful streak, as buyers weigh sturdy synthetic intelligence and semiconductor momentum towards dividend-related buying and selling, a weak yen, excessive bond yields and lingering uncertainty over the Bank of Japan’s subsequent transfer.
The last buying and selling day for a lot of September-end dividend rights is anticipated to form the session. Investors who wish to obtain interim dividends or shareholder advantages for a lot of firms with September 30 document dates should maintain the shares by means of the September 28 shut, making the day an necessary deadline for banks, insurers, buying and selling homes, producers and different high-dividend names.
That dividend demand helped broaden the market on September 25, when the Nikkei rose 850 factors and TOPIX climbed 53.29 factors to 4,128.59. Banks had been the strongest sector, whereas semiconductor and AI-linked shares equivalent to Tokyo Electron, Advantest, Kioxia and Ibiden lifted the Nikkei.
The speedy query for September 28 is whether or not that broad assist can proceed, or whether or not buyers take earnings earlier than the September 29 ex-dividend adjustment. The Nikkei has already moved sharply from its mid-September lows, and the dividend calendar could encourage each last-minute shopping for and warning over what occurs as soon as the rights date passes.
The Nikkei’s technical image has improved. The index reclaimed 65,000 after Silver Week after which moved above 66,000 on September 25, supported by chip shares, banks and renewed confidence in world AI demand.
The subsequent take a look at is whether or not the Nikkei can maintain above 66,000 and make one other try towards the higher 66,000 vary. A agency shut would recommend that the rebound has moved past a short-term futures-led restoration. A weak session would elevate the danger that the current rally was pushed partly by dividend demand and quick protecting.
TOPIX will probably be simply as necessary because the Nikkei. On September 24, the Nikkei rose whereas TOPIX slipped, exhibiting a slim AI-led rally. On September 25, TOPIX rose strongly as banks and dividend-sensitive shares joined the advance. For September 28, buyers will watch whether or not that broader participation continues.
A market led solely by Tokyo Electron, Advantest and MushyBank Group can raise the Nikkei shortly, nevertheless it stays weak to profit-taking. A stronger TOPIX would recommend more healthy demand throughout financials, exporters, worth shares and domestic-demand names.
The dividend theme ought to hold banks in focus. Mitsubishi UFJ Financial Group, Sumitomo Mitsui Financial Group, Mizuho Financial Group, Resona Holdings and regional banks attracted shopping for on September 25 as buyers positioned for interim dividends and better rates of interest.
Banks stay one of many clearest beneficiaries of BOJ normalization as a result of larger charges can enhance lending margins and funding revenue. However, the sector has already priced in a major quantity of rate-hike optimism, so the following stage relies on whether or not buyers consider the BOJ will elevate charges once more in December or early 2027.
The BOJ raised its coverage charge to 1.25% on September 18, the very best stage in 31 years. The market initially handled the choice as much less hawkish than feared due to the cut up vote and cautious steering, which weakened the yen and supported equities.
That response stays necessary for September 28. If buyers proceed to see the BOJ as gradual somewhat than aggressive, development and expertise shares could keep supported. If bond yields rise once more or BOJ officers sound extra hawkish, rate-sensitive sectors might face stress.
Japanese authorities bond yields stay one of many largest dangers. The 10-year yield has moved above 3% and touched round 3.121%, its highest stage since 1996. That modifications the funding surroundings for equities, banks, insurers, mortgages, company borrowing and authorities funds.
Higher yields assist monetary shares, however they stress high-valuation development shares by elevating the low cost charge utilized to future earnings. They additionally enhance the federal government’s debt-servicing burden, making fiscal self-discipline a bigger challenge for buyers.
For September 28, the bond market will probably be a key information. A secure or barely decrease JGB yield would assist equities, particularly semiconductor and AI-related shares. A renewed rise in 10-year or super-long yields would elevate concern that the rally is working right into a higher-rate ceiling.
The yen is one other central sign. The dollar-yen charge has been buying and selling close to the 158 vary, leaving the forex weak even after the BOJ’s charge hike. That helps exporters however retains imported-inflation and intervention dangers alive.
A weaker yen helps automakers, equipment makers, electronics firms and precision-equipment producers by rising the yen worth of abroad earnings. It additionally helps the Nikkei as a result of many giant exporters and expertise firms profit from abroad income translation.
However, yen weak point stays a burden for households and importers. It raises the price of vitality, meals, uncooked supplies and client items, particularly when oil costs stay elevated.
Finance Minister Satsuki Katayama has saved forex stability in focus, and markets stay alert to intervention danger if the yen strikes shortly towards 160. A sudden transfer in dollar-yen might shortly have an effect on sentiment on September 28.
For exporters, Toyota, Honda, Sony Group, Fanuc, Keyence, Komatsu and precision-equipment makers will probably be watched intently. A secure weak yen might assist them, whereas a pointy yen rebound would doubtless revive earnings issues.
Honda could stay in focus after current shopping for linked to its next-generation hybrid automobile technique in North America. Automakers stay delicate to the yen, U.S. demand, tariffs and the stability between hybrid and electrical automobile funding.
The AI and semiconductor commerce will stay the primary driver of the Nikkei. Tokyo Electron and Advantest had been the 2 most necessary contributors to the September 25 rally, whereas Kioxia, Ibiden, Murata Manufacturing, TDK, Taiyo Yuden, Lasertec, Screen Holdings and different chip-related names additionally drew consideration.
U.S. expertise shares completed larger on September 25, with Microsoft rising after unveiling new Copilot-related AI capabilities. That supplies a constructive abroad lead for Japanese AI and software-related names, though the rally in U.S. shares was not as highly effective as the sooner surge seen throughout Japan’s Silver Week break.
The Philadelphia Semiconductor Index had weakened earlier within the week, however Japanese chip shares nonetheless rose on September 25. That suggests home elements, together with the weak yen, dividend demand and positioning, had been stronger than the in a single day U.S. chip lead.
For September 28, buyers will watch whether or not Japanese semiconductor shares can hold rising with out a recent U.S. catalyst. If Tokyo Electron and Advantest proceed to achieve, the Nikkei could stay agency. If they fade, the index might battle even when TOPIX is supported by dividend shopping for.
Kioxia stays a key barometer for memory-sector confidence. The firm is tied to high-bandwidth reminiscence, AI servers and data-center storage demand, however its share worth has been extremely risky since July. Strength in South Korean reminiscence shares would assist sentiment, whereas weak point in Samsung Electronics or SK Hynix would doubtless weigh on Tokyo’s chip complicated.
Fujikura, Furukawa Electric and Sumitomo Electric stay necessary second-wave AI infrastructure names. Their publicity to optical fiber, cables, high-speed networks and data-center infrastructure retains them intently tied to the bodily buildout required by synthetic intelligence.
MushyBank Group may even be intently watched. The stock didn’t absolutely be a part of the September 25 rally due to concern over delays in Oracle data-center energy provide initiatives, nevertheless it stays Tokyo’s most seen proxy for world AI funding by means of its publicity to OpenAI, Arm, robotics and digital infrastructure.
MushyBank’s funding plans stay necessary as a result of the size of its AI technique relies upon closely on capital-market entry. A restoration within the stock would assist the Nikkei, whereas renewed weak point would restrict the index’s upside even when chip-equipment shares keep agency.
The AI commerce remains to be highly effective, however buyers are actually extra selective. They are separating chip gear, reminiscence, optical fiber, platforms, software program and data-center infrastructure based on earnings visibility, valuation, funding wants and publicity to bottlenecks equivalent to energy provide.
Oil will stay a significant macro issue. Crude costs have eased from current highs, serving to scale back inflation stress, however vitality prices stay excessive sufficient to have an effect on Japan’s commerce stability, family budgets and company margins.
Japan imports most of its vitality, so oil costs feed immediately into gasoline, electrical energy, aviation gasoline, transport, logistics, chemical compounds and manufacturing. An extra decline in crude would assist Japanese equities and family sentiment. A rebound would revive inflation issues, particularly with the yen close to 158.
Households stay underneath stress regardless of bettering wages. Consumers nonetheless face excessive prices for groceries, gasoline, electrical energy, transport and providers. That means retailers, eating places, journey firms and consumer-product makers stay delicate as to whether wage positive aspects are sufficient to cowl rising on a regular basis bills.
For firms, the important thing challenge stays pricing energy. Firms with sturdy manufacturers, secure demand, recurring income or publicity to long-term funding are higher positioned. Companies with out pricing energy face margin stress if wages, vitality, logistics and borrowing prices hold rising.
The September 28 session may present whether or not buyers proceed rotating into worth and dividend shares. Trading homes, insurers, banks, telecoms and producers with sturdy payouts might appeal to demand by means of the shut, however the ex-dividend adjustment on September 29 could make buyers cautious about chasing costs too aggressively.
Mitsubishi Corp., Mitsui & Co., Itochu, Sumitomo Corp. and Marubeni stay necessary gauges of worth and shareholder-return demand. They have lagged some AI names just lately, however dividend shopping for and commodity publicity might assist them if buyers search stability after the Nikkei’s quick rally.
Insurers equivalent to Tokio Marine and MS&AD stay tied to the yield story. Higher charges can enhance funding returns, however speedy bond-market strikes may create volatility in portfolios.
Retailers and importers stay extra sophisticated. A weak yen hurts import prices, however easing oil may also help. Nitori and comparable yen-benefit names could battle if dollar-yen stays close to 158, whereas firms with sturdy home pricing energy could fare higher.
Prime Minister Sanae Takaichi’s authorities stays a part of the market backdrop. The authorities is making an attempt to assist households, enhance protection spending and fund long-term strategic funding whereas bond yields and debt-servicing prices rise.
The authorities’s development technique targets large-scale private and non-private funding by means of fiscal 2040 in semiconductors, synthetic intelligence, vitality safety, protection, shipbuilding, robotics, house and different strategic sectors.
That technique helps lots of the firms main the market, together with chip-equipment makers, supplies suppliers, optical-network companies, power-system firms, data-center infrastructure suppliers and defense-related producers.
However, larger rates of interest make fiscal self-discipline extra necessary. Investors will proceed watching price range discussions, debt-service assumptions and whether or not strategic funding will be funded with out undermining confidence in public funds.
The worldwide backdrop stays combined. U.S. shares rose on September 25 as AI optimism helped offset concern over oil costs and Treasury yields, however the week was risky due to uncertainty over AI winners and losers, Middle East dangers and excessive U.S. yields.
The U.S. Federal Reserve stays dedicated to combating inflation, and markets proceed to look at the potential of one other charge enhance. High U.S. yields assist the dollar and complicate the BOJ’s effort to stabilize the yen.
If U.S. yields hold rising, Japanese shares could face two opposing forces: exporter assist from a weaker yen, however valuation stress from larger world bond yields. That stress is prone to stay a central theme on September 28.
U.S.-China relations additionally stay necessary after the most recent Trump-Xi assembly produced symbolism however no main breakthroughs on AI, commerce, Taiwan or the Iran battle. Japanese exporters and expertise firms stay uncovered to any shift in U.S.-China supply-chain coverage.
South Korean semiconductor shares will probably be one other early indicator. Overseas buyers more and more deal with Japanese chip-equipment makers, South Korean reminiscence producers, Taiwanese foundries and U.S. AI shares as one linked expertise commerce.
If Seoul opens agency, Japanese AI and chip names could obtain one other increase. If Korean reminiscence shares weaken, Tokyo’s semiconductor complicated might face profit-taking.
What to look at on September 28: whether or not the Nikkei can maintain above 66,000, whether or not TOPIX continues to catch up, whether or not dividend shopping for helps banks and worth shares, and whether or not semiconductor shares can lengthen positive aspects with out a sturdy new U.S. chip lead.
The yen close to 158 to the dollar stays an important home market sign. A transfer towards 160 would assist exporters however revive intervention and inflation issues. A rebound towards 153 would ease import prices however stress exporters and carry trades.
JGB yields are the second key sign. A secure 10-year yield would assist the rally, whereas one other rise towards recent multi-decade highs would stress development shares and lift fiscal issues.
The third sign is breadth. If banks, insurers, buying and selling homes, exporters and domestic-demand shares rise alongside semiconductor names, the rally will look more healthy. If positive aspects slim once more to Tokyo Electron, Advantest and some AI-linked names, the market will stay weak.
September 28 is prone to be formed by the collision of three forces: dividend shopping for earlier than the rights deadline, momentum from AI and semiconductor shares, and warning over the weak yen and excessive bond yields. The Nikkei enters the session with sturdy upward momentum, however the market’s sturdiness will depend upon whether or not TOPIX can hold tempo and whether or not shopping for survives past the dividend calendar.