


TOKYO –
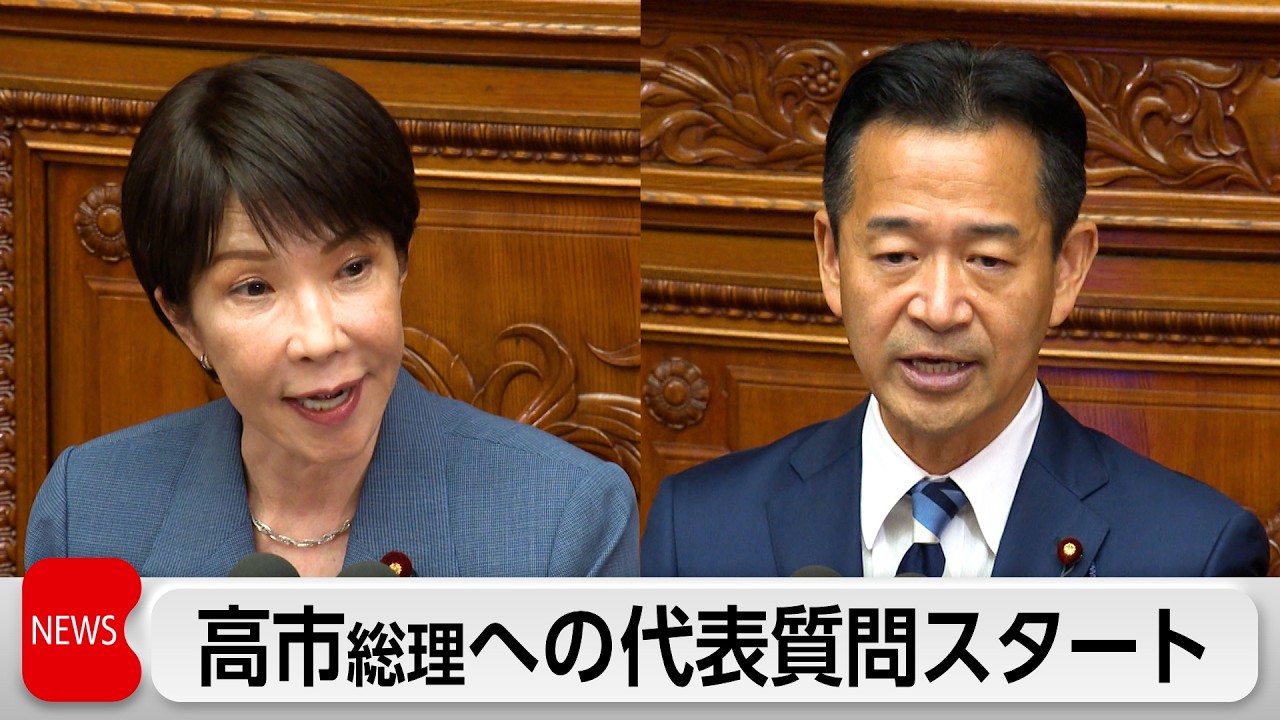
Prime Minister Sanae Takaichi defended her plan to chop the consumption tax on meals and supply help funds to staff within the House of Representatives on October 7, searching for to maintain family aid on the heart of her autumn Diet agenda whereas markets proceed to check the federal government’s fiscal credibility.
Takaichi advised lawmakers that the federal government’s proposed tax minimize and funds are supposed to assist households deal with rising costs and be sure that staff really feel the advantages of financial development. Her remarks got here as opposition events pressed the administration over the way it plans to fund the measure with out rising Japan’s already heavy debt burden.
The authorities plans to scale back the consumption tax on meals and drinks from 8% to 1% for 2 years starting in April 2027. It additionally plans to offer funds that may successfully cowl the remaining 1% burden in the course of the interval. The coverage is the administration’s primary reply to voter frustration over meals costs, which have grow to be one of many clearest day by day indicators of inflation for households.
The political enchantment is easy. Food costs have an effect on nearly each family, and a tax minimize is simpler to clarify than a extra complicated subsidy program. Takaichi desires the measure to point out that her authorities isn’t targeted solely on protection, industrial coverage and the yen, however can be addressing day by day dwelling prices.
But the fiscal rationalization stays incomplete. The tax minimize is predicted to create a big income shortfall, and Finance Minister Satsuki Katayama has repeatedly mentioned the federal government will keep away from deficit-financing bonds. That pledge is politically vital as a result of bond traders are already involved about Japan’s debt trajectory, nevertheless it leaves the federal government beneath strain to current a reputable various funding plan.
Takaichi has tried to reassure markets by promising to regulate new bond issuance and reply shortly if monetary instability emerges. In her coverage speech to parliament this week, she emphasised fiscal self-discipline whereas additionally defending focused spending for development, financial safety and family aid. The message was designed to inform traders that her administration’s energetic fiscal stance doesn’t imply abandoning price range restraint.
The bond market stays unconvinced sufficient to maintain strain on the federal government. Japan’s long-term borrowing prices have risen sharply as traders weigh larger inflation, lowered Bank of Japan bond purchases and concern over future debt issuance. Thirty-year Japanese authorities bond yields just lately rose to report ranges, whereas 10-year yields have remained close to multi-decade highs.
That issues politically as a result of larger yields make Takaichi’s agenda dearer. The authorities is making an attempt to chop meals taxes, help households, broaden protection, strengthen financial safety and promote a 370 trillion yen public-private funding roadmap via fiscal 2040. Each coverage has a transparent political rationale, however collectively they elevate the query of how a lot the state can promise whereas borrowing prices are rising.
The Bank of Japan is now central to that debate. New BOJ Policy Board member Ayano Sato, beforehand considered as one of many extra cautious voices on tightening, has signaled help for gradual future charge hikes if financial information proceed to justify them. Her feedback counsel that even dovish members could also be transferring towards acceptance of additional normalization as inflation dangers persist.
Sato opposed the BOJ’s September charge hike to 1.25%, citing weak consumption and gradual motion in some underlying worth measures. But she has since acknowledged that inflation dangers are tilted upward, partly as a result of rising oil costs and world vitality uncertainty might maintain import prices excessive. She mentioned charge changes ought to proceed in levels and depend upon consumption and revenue traits.
Her place is necessary for Takaichi as a result of it narrows the federal government’s room to imagine that the BOJ will stay cautious. If extra board members settle for gradual hikes, the central financial institution might maintain coverage on a tightening path at the same time as the federal government worries about borrowing prices and development.
A stronger BOJ stance might assist help the yen and scale back import-driven inflation, which might be politically useful for households. But larger charges additionally enhance debt-servicing prices, strain bond markets and complicate the federal government’s fiscal plans. This is the core rigidity dealing with Takaichi: the identical financial tightening that may assist stabilize costs might make her tax and spending agenda more durable to finance.
Currency markets are reflecting that rigidity. The yen weakened because the dollar strengthened on October 7, with traders targeted on U.S. Federal Reserve coverage, larger oil costs and the likelihood that Japan’s charge path could also be slower than some had anticipated. Rising oil costs are particularly uncomfortable for Japan as a result of the nation relies upon closely on imported vitality, making the change charge immediately related to family payments and enterprise prices.
Takaichi has argued that one of the simplest ways to help confidence within the yen is to boost Japan’s financial competitiveness. Her authorities says strategic funding in areas resembling synthetic intelligence, semiconductors, shipbuilding, vitality, area and quantum know-how will strengthen the financial system’s provide capability and enhance long-term confidence within the forex.
That argument is central to Takaichi’s financial coverage. She desires to point out that Japan can help households within the brief time period whereas rebuilding industrial energy over the long run. But markets are prone to maintain asking whether or not the federal government can fund that transition with out counting on debt or pressuring the BOJ to maintain monetary circumstances unfastened.
The authorities can be contemplating one other supplementary price range, this time targeted primarily on catastrophe aid and reconstruction after earthquakes and heavy rain. The proposed package deal is predicted to be comparatively small in contrast with earlier stimulus budgets and might be compiled in November for passage early subsequent 12 months.
The transfer could also be politically simpler to defend than broad financial stimulus. Disaster aid is mostly seen as vital spending, and Takaichi has beforehand mentioned she desires to scale back reliance on frequent giant supplementary budgets. A narrowly targeted catastrophe package deal would permit the federal government to answer affected areas whereas making an attempt to take care of its message of fiscal restraint.
Still, even a smaller further price range provides to the impression that spending wants are multiplying. The administration already faces calls for for tax aid, protection spending, reconstruction, social safety and development funding. The problem for Katayama shall be to clarify how every package deal suits inside an general borrowing plan that traders can settle for.
Business sentiment presents a combined image. A Reuters Tankan ballot confirmed main producers’ confidence at its highest degree in almost 5 years, helped by semiconductor-related demand and energy in precision equipment. But service-sector sentiment weakened sharply, with meals producers hit by uncooked materials prices and subdued shopper spending.
That cut up is politically necessary. It provides Takaichi proof that elements of the manufacturing and know-how financial system are responding to the federal government’s development themes. But it additionally exhibits that households and home service industries stay beneath strain from inflation and weak buying energy.
The opposition is prone to concentrate on that divide. It can argue that the federal government is highlighting semiconductor demand and strategic funding whereas peculiar households and food-related companies proceed to battle. Takaichi will counter that the tax minimize, funds and funding roadmap are designed to bridge that hole by delivering aid now and development later.
The Diet debate is subsequently transferring towards a credibility take a look at. Opposition events will press the federal government on when the food-tax minimize will take impact, how the help funds shall be distributed, how the income loss shall be lined, and whether or not the coverage can actually stay short-term. They may also ask whether or not larger bond yields and BOJ tightening make the federal government’s plans much less lifelike.
Takaichi’s benefit is that the coverage is simple for voters to grasp. Cutting the meals tax from 8% to 1% provides the federal government a direct message on costs. Her problem is that the identical simplicity makes the funding downside extra seen. If the administration can not clarify the place the cash will come from, the tax minimize might grow to be an emblem of fiscal danger fairly than family aid.
The October 7 political image exhibits Takaichi making an attempt to maintain management of the cost-of-living agenda whereas defending market confidence. The authorities desires voters to see tax aid and employee help. Investors desire a funding plan and limits on bond issuance. The BOJ desires room to answer inflation. Opposition events need to body the tax minimize as a promise made earlier than the cash was discovered.
The central query is whether or not Takaichi can join the items earlier than the Diet debate hardens. If Katayama presents credible funding, if the BOJ’s gradual tightening stabilizes the yen with out stunning bond markets, and if catastrophe aid stays narrowly targeted, the federal government could possibly defend its autumn agenda. If yields rise additional or the tax-cut funding stays imprecise, the food-relief plan might grow to be the primary level of assault towards Takaichi’s financial management.
What To Watch Next
The Diet debate over the food-tax minimize will stay the primary home political focus, particularly the funding construction and timing of employee help funds.
Finance Minister Satsuki Katayama will face strain to clarify how the federal government can keep away from deficit-financing bonds whereas protecting the tax-cut income shortfall.
BOJ communication shall be intently watched after Ayano Sato signaled help for gradual future charge hikes regardless of opposing the September transfer.
The yen stays a key political sign, particularly as larger oil costs enhance Japan’s import burden.
The potential disaster-relief further price range will take a look at whether or not Takaichi can reply to reconstruction wants whereas preserving supplementary spending restricted.
Bond yields stay a very powerful market indicator for the federal government’s fiscal credibility.
Opposition events are prone to join the food-tax minimize, bond-market strain and BOJ independence right into a broader assault on Takaichi’s financial administration.